Alarming Health Realities...
- In 20 years, the elderly will outnumber the youth by a ratio 4:1
- Aging workforce is the biggest economic challenge over the next decades
- Heart disease is the number one cause of mortality in the Philippines
- Medical inflation hits nosebleed levels, 3-4 times economic inflation
- Cost of medicines in the Philippines is 600% higher than our neighboring Asian countries
- Health conditions in the Philippines remain among the poorest in East Asia
- More and more people die not because of no doctor or no medicine but because of money
Kaiser International Health Group Inc.
We are duly accredited with the Department of Health (DOH). Our Company is likewise, registered with the Securities and Exchange Commission (SEC) on June 08, 2004 as a Health Care Provider with an Authorized Capital Stock of Php 160M.
Kaiser International Health Group Inc. is far more than an HMO. While most HMOs cater to both group and individual accounts, Kaiser's product is geared to address the long-term health care needs of individuals especially after their employment and retirement years.
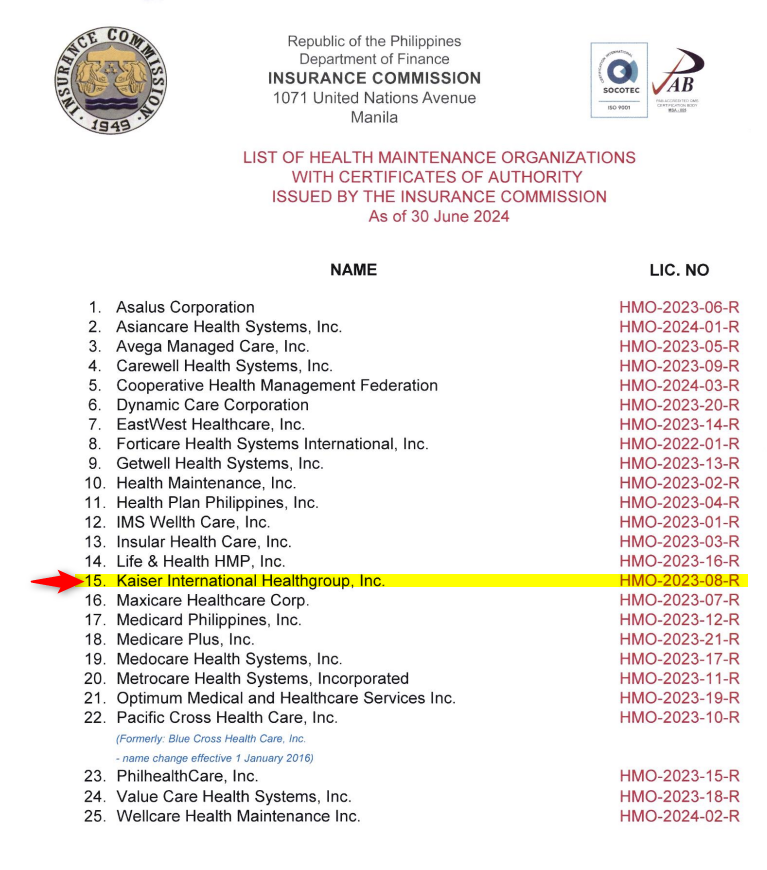
REGISTERED SA INSURANCE COMMISSION
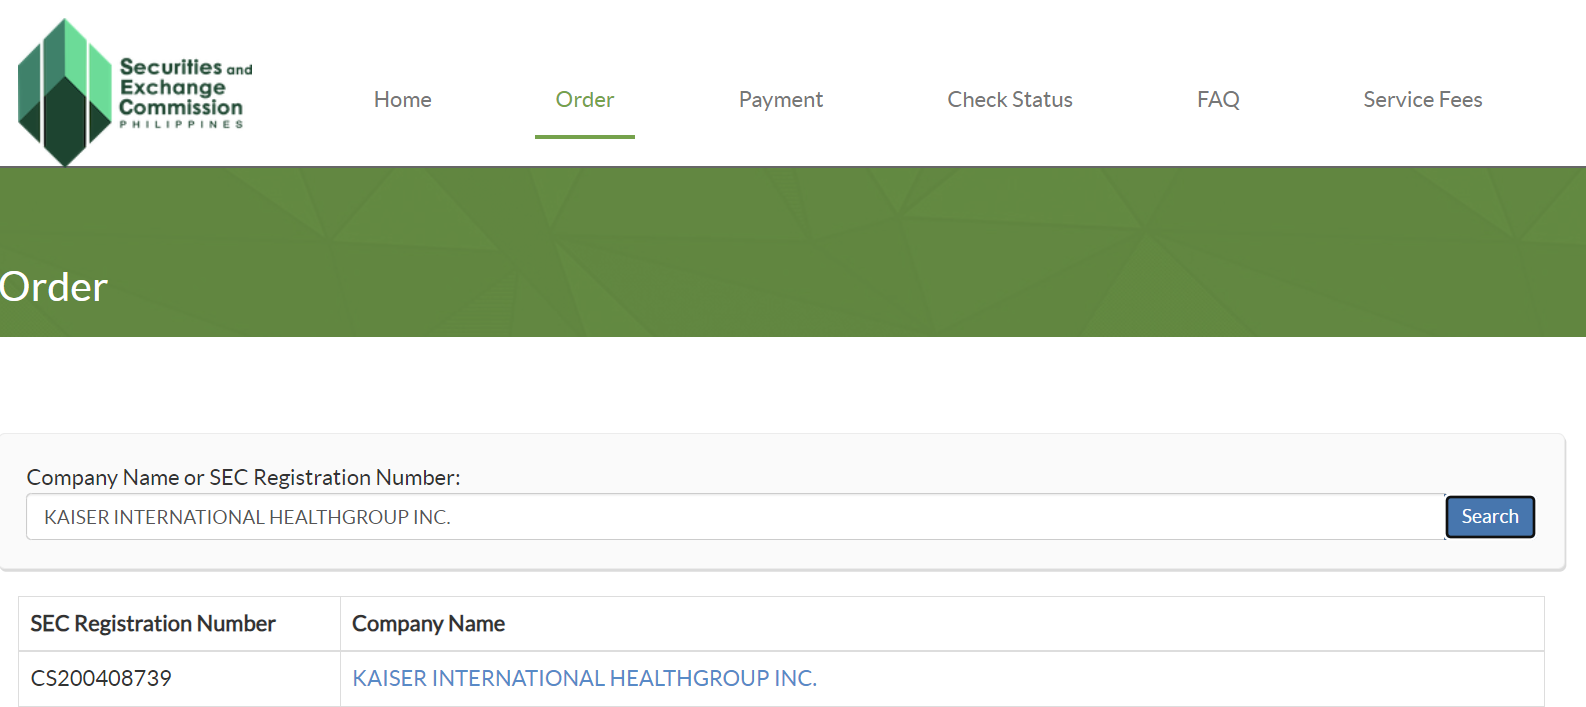
SEC REGISTRATION
SEC Registration Number: CS200408739
Company Name: KAISER INTERNATIONAL HEALTHGROUP INC.
MEMBER OF PAHMOC - PHILIPPINE ASSOCIATION OF HEALTH MAINTENANCE ORGANIZATION COMPANIES
HMO MEMBERS - KAISER INTERNATIONAL HEALTHGROUP INC.
KAISER-7-YEARS-SAVING-PROGRAM-EXPLAINED
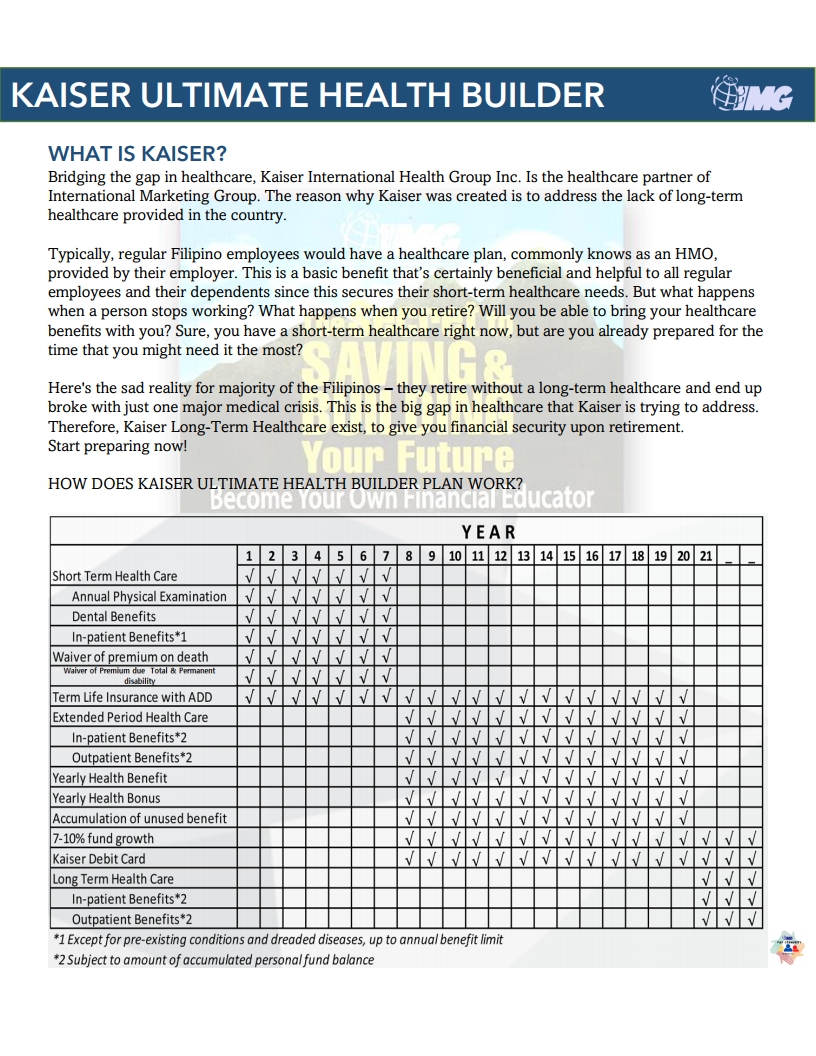
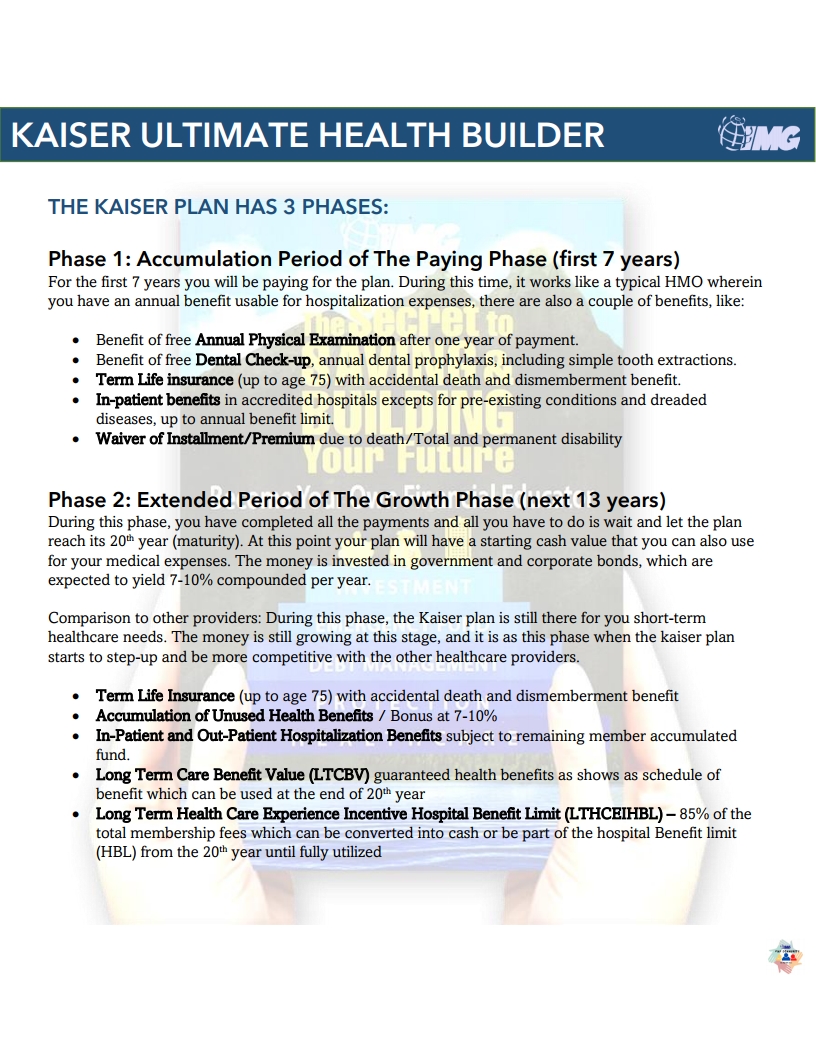
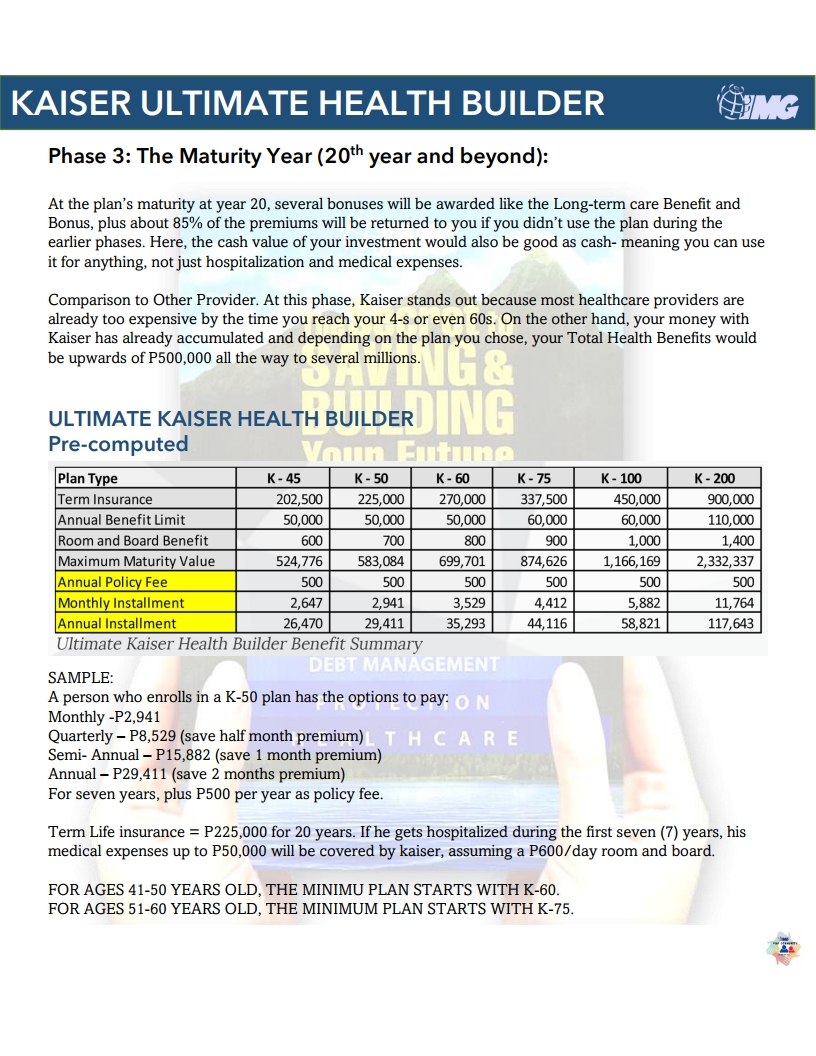
The Three (3) Important Phases of a Kaiser Plan
We are SBPro
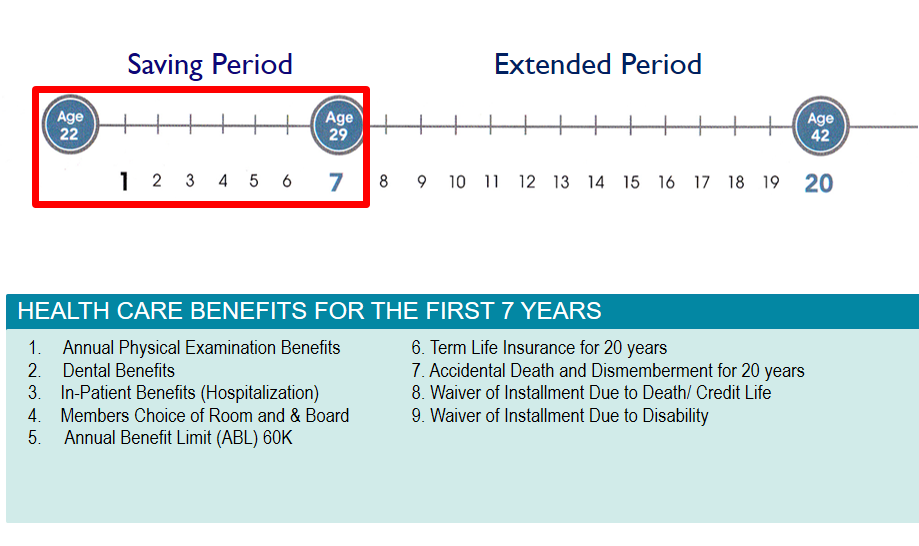
FIRST PHASE: ACCUMULATION PERIOD OR THE PAYING PERIOD (FIRST 7 YEARS)
For the first 7 years you will be paying for the plan.
During this time, it works like a typical HMO wherein you have an annual benefit usable for hospitalization expenses. These are also a couple of benefits, like:
1. Benefit of free Annual Physical Examination after one year of payment.
Physical Examination, Chest X-Ray, Routine Fecalysis, Routine Urinalysis, Complete Blood Count
ECG for Members above 35 and Pap Smear for Female Members above 35 years old or as required.
2. Benefit of free Dental Check-up and the following;
Unlimited Dental Check Ups
Unlimited Simple tooth extraction
Once A year Free Dental Prophylaxis
Recementation of jacket, crowns, inlays, on lays and
Minor adjustment of Dentures
3. Term life Insurance (up to age 75) with accidental death and dismemberment riders.
4. In-Patient benefits in accredited hospitals except for pre-existing conditions and dreaded diseases, up to plan annual benefit limit.
5. Waiver of installment/ Premium due to death/ total and permanent disability.
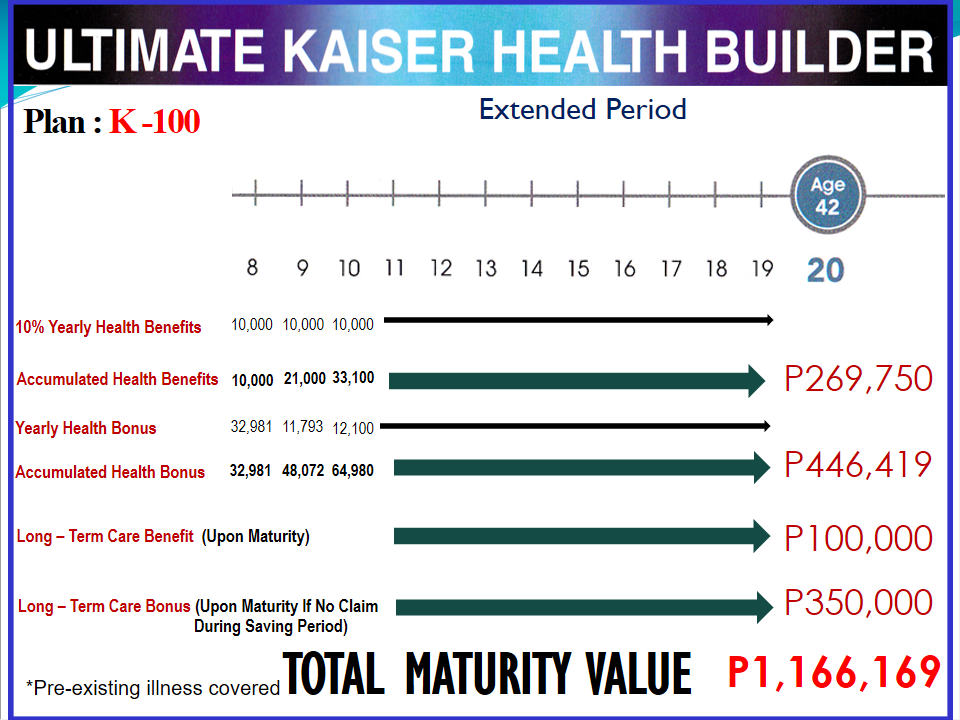
SECOND PHASE: EXTENDED PERIOD OR THE GROWTH PERIOD (NEXT 13 YEARS)
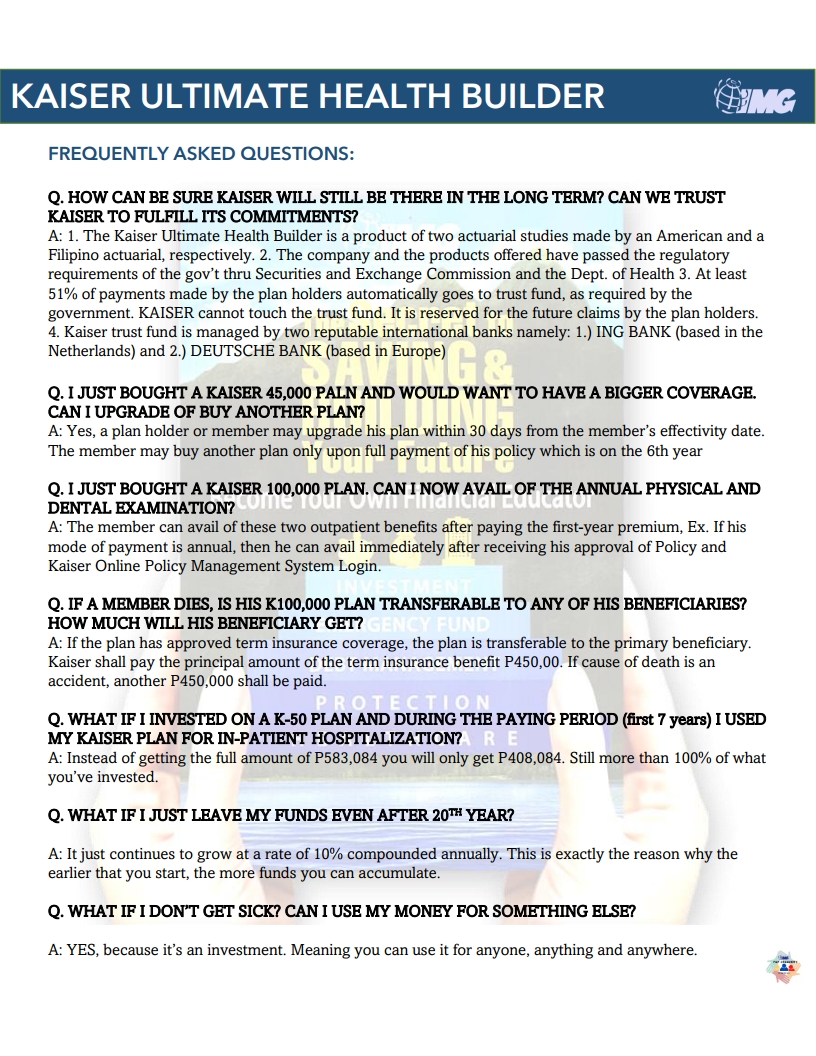
During this phase, you have completed all the payments and all you have to do is wait and let the plan reach its 20th year (maturity) at this point your will have a starting cash value that you can also use for your medical expenses. The money is invested in government and corporate bonds, which are expected to yield 3% - 10% compound per year.
Comparison to other providers: during this period, the Kaiser plan is still there for your short-term healthcare needs. The money is still growing at this stage and it is at this period when the Kaiser plan starts to step-up and be more competitive with the other healthcare providers.
• Term life Insurance (up to age 75) with accidental death and dismemberment riders.
• Accumulation of unused Health Benefits at 3%-10%
• In-Patient and Out-Patient Hospitalization Benefits subject to remaining member accumulated fund.
• Accumulation of unused Health Bonus at 3-10%
We are SBPro
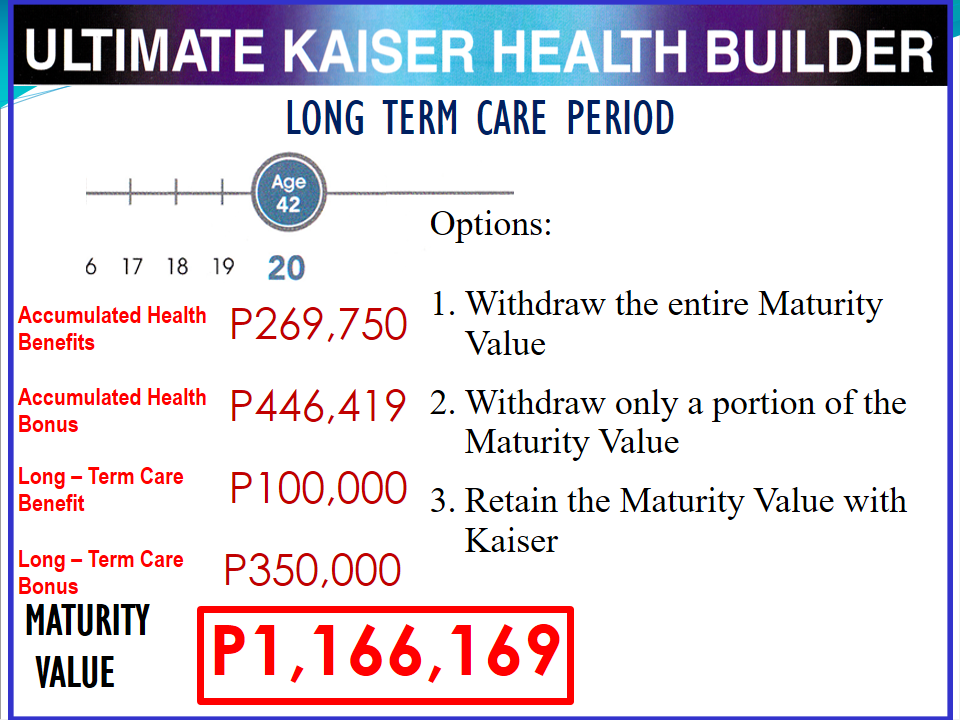
THIRD PHASE: THE MATURITY YEAR/ LONG-TERM CARE PERIOD (20TH YEAR ONWARDS)
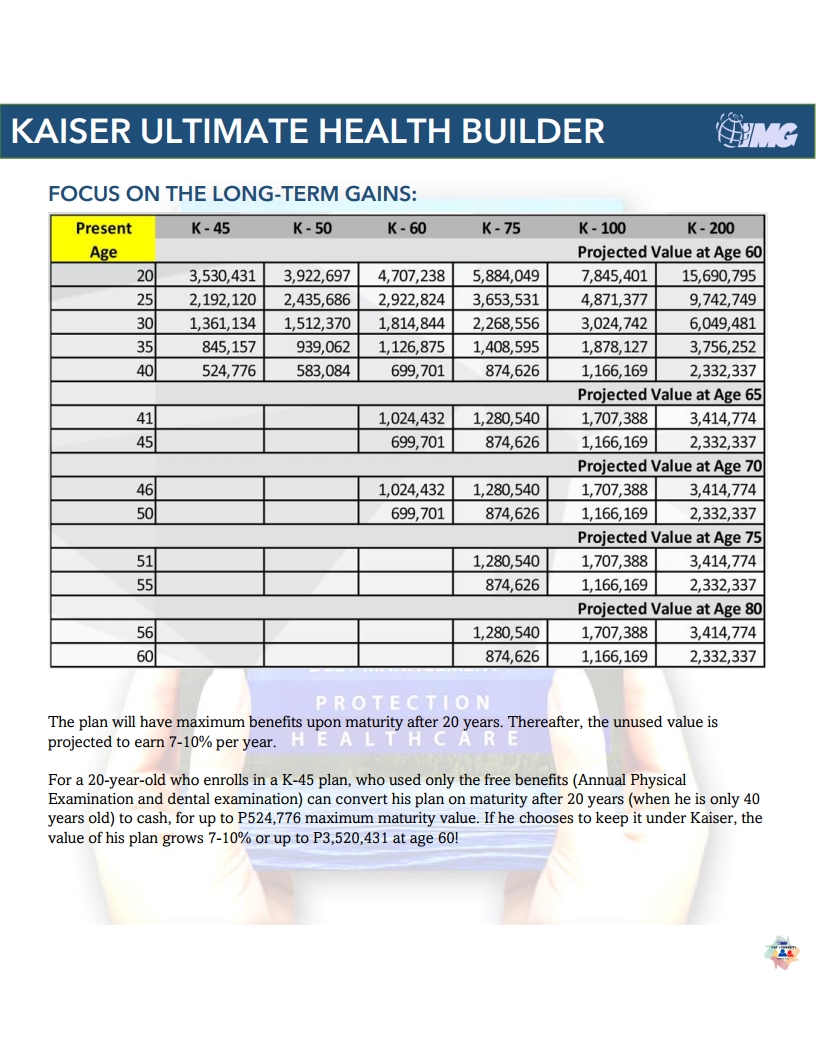
At the plan’s maturity at 20th year, several bonuses will be awarded like the Long-term care benefit and bonus, plus about 85% of the premiums will be returned to you if you didn’t use the plan during the earlier stages, here, the cash value of your investment would also be good as cash- meaning you can use it for anything not just hospitalization and medical expenses.
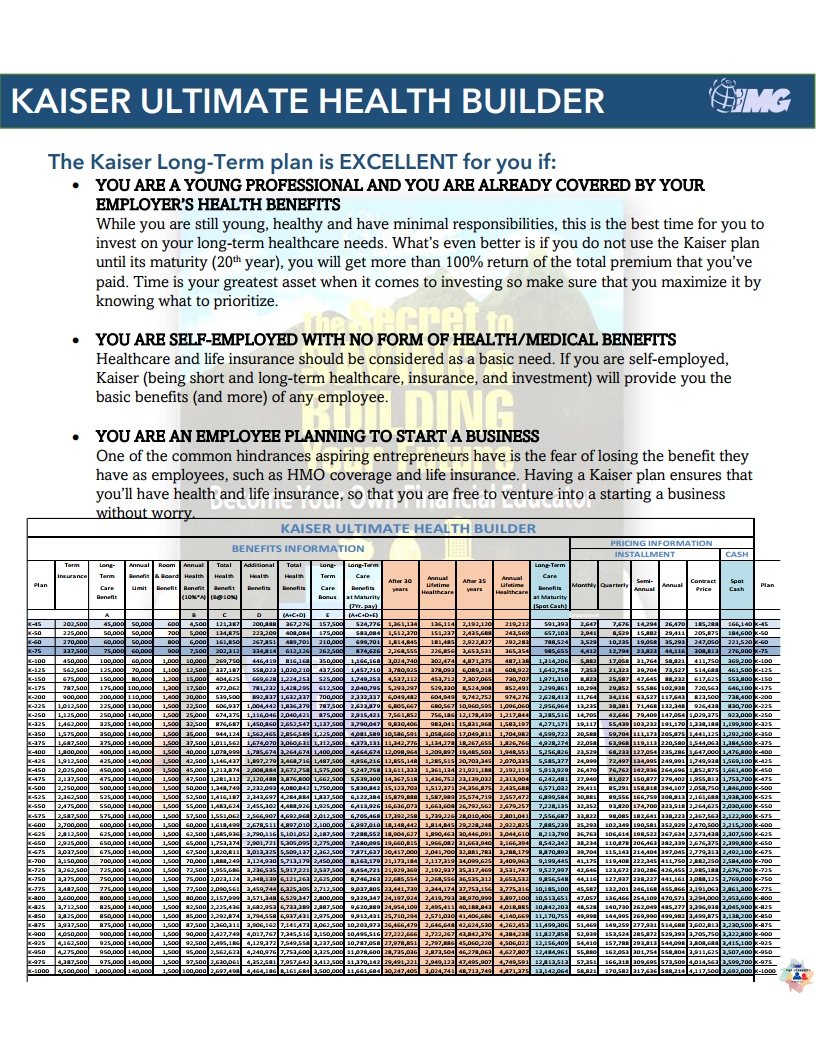
Comparison to other providers: at this Period, Kaiser stands out because most healthcare providers are already too expensive by the time you reach your 40s or even 60s. On the other hand, your money with Kaiser has already accumulated and depending on the plan you chose, your Total Health Benefits would be upwards of P500,000 all the way to several millions.
There are 3 Kinds of Healthcare
Short-term healthcare, Long-term healthcare, and Senior Care.
Short-term Healthcare
Ito ang healthcare na binabayaran taon-taon up to age 60 (magamit man natin o hindi).
Kapag nagpa-check up tayo o na-confine, sagot ng healthcare company ang bill natin. Kapag hindi natin nagamit, hindi carried over ang benefits the following year.
Kung empleyado ka, binabayaran ito ng kumpanya HABANG nagta-trabaho ka pa. Oras na mag-resign ka, o mag-retire na, hindi ka na covered.
Tanong: Kailan lumalabas ang mga mas seryosong sakit - habang bata, o kapag tumanda na tayo?
Senior Care
Ito naman ang yearly healthcare for Seniors age 60 pataas.
Since alam ng healthcare companies na madalas nang magkasakit ang mga Senior, ito ang pinakamahal na healthcare.
Long-term Healthcare
Ito ang healthcare na pwede nating simulan habang bata pa tayo, o habang hindi pa tayo Senior (10 to 60 years old).
Ito ang pinakamurang healthcare dahil pitong (7) taon lang nating huhulugan, pero covered tayo hanggang pagtanda.
The KAISER Long-Term Healthcare is a 3-in-1 product.
LONG-TERM HEALTHCARE
Ang mga traditional HMO (Health Maintenance Organization) ay short-term lang. Magbabayad ka ng annual premium for a certain healthcare coverage. Magamit mo ito or hindi ay babayaran mo pa rin every year kung gusto mong ipagpatuloy ang healthcare coverage.
Sa Kaiser, puwedeng maging short-term at long-term. Kung nag-avail ka nito at biglang nagkasakit magagamit mo ang healthcare benefits. Paano naman kung hindi magamit? Okay lang! Dahil si Kaiser ay long-term healthcare din kung saan ang hinuhulog mo ay hindi masasayang at magagamit mo pa rin in future needs.
LIFE INSURANCE
Sa traditional HMO (Health Maintenance Organization) kapag sinabing healthcare ay Pure Healthcare lang.
Sa Kaiser, hindi lang siya basta healthcare. May Life Insurance coverage din na kung saan ay protected ang pamilya.
Halimbawang may mangyari sa policy holder ay makakatanggap ang beneficiaries nito ng instant money mula sa Insurance Company.
Bukod pa doon ay may Waiver of Installment due to Death, Waiver of Installment due to Total and Permanent Disability at Transfer of Kaiser Policy to the Principal Beneficiary.
SAVINGS & INVESTMENTS
Bukod sa healthcare at life protection, ang kaiser ay may investment din.
Kung healthy ka at hindi mo nagagamit ang healthcare coverage bibigyan ka pa ng BONUS ni kaiser sa Maturity ng iyong 3-in-1 Saving Plan.
Makukuha mo ang lump sum sa 20th year ng iyong plan. May option ka rin na i-retain lang ito upang lumago pa ang pera mo.
Imagine? Nag-save ka lang sa loob ng 7 years may makukuha kang malaking halaga sa Maturity Period ng Saving Plan mo. Para ka ring may pension na pwede mong kuhanin buwan-buwan dahil good as cash itong investment mo.
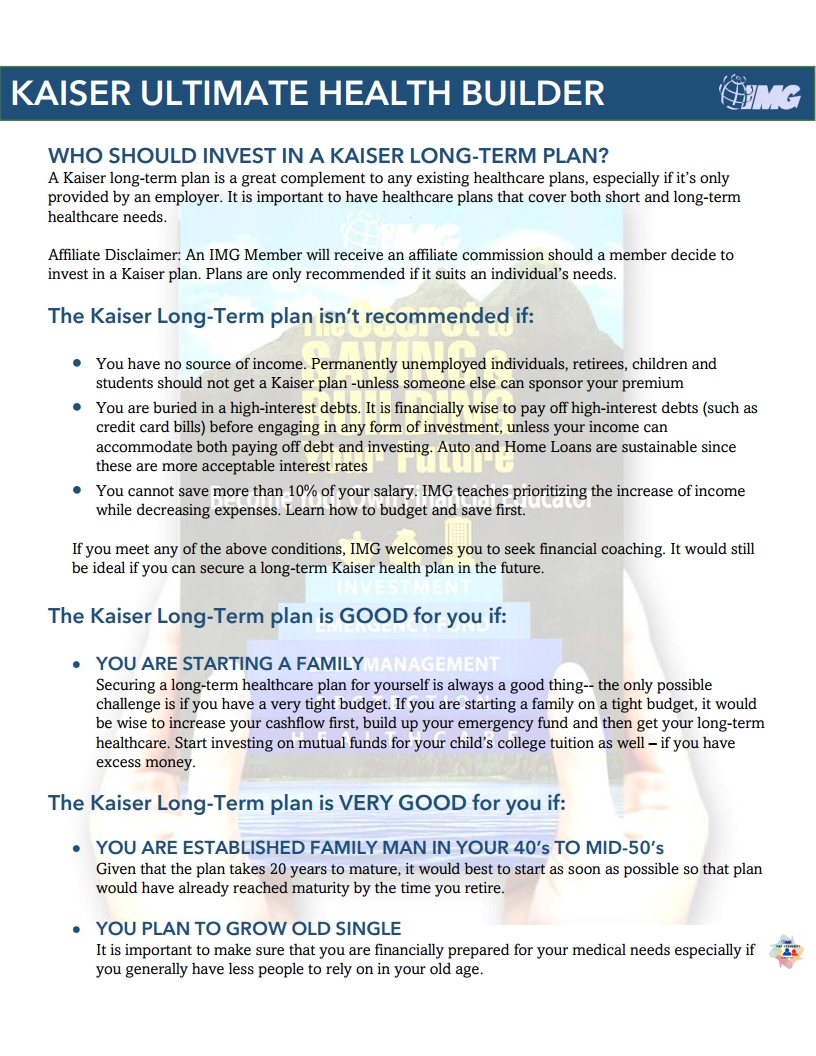
WHO IS ELIGIBLE TO GET KAISER LONG TERM CARE?
10 years old to 60 years old only.
Lahat ng Pilipino, even OFWs.
Even the minimum wage earner, dahil affordable ito.
Puwede rin sa mga high risk jobs like Police, Firefighters, etc.
At Kahit pa may mga existing illness na, siguraduhin lang na i-declare ito sa kaiser application form. This is subject for approval. (case to case basis)
Watch our financial coaching video and learn the following:
What are the Major Financial Needs of every Filipino Family.
How Kaiser Long-term care works
Why Kaiser is the complete solution for your family
BAKIT NGA BA MAGANDANG KUMUHA NG KAISER 3-IN-1?
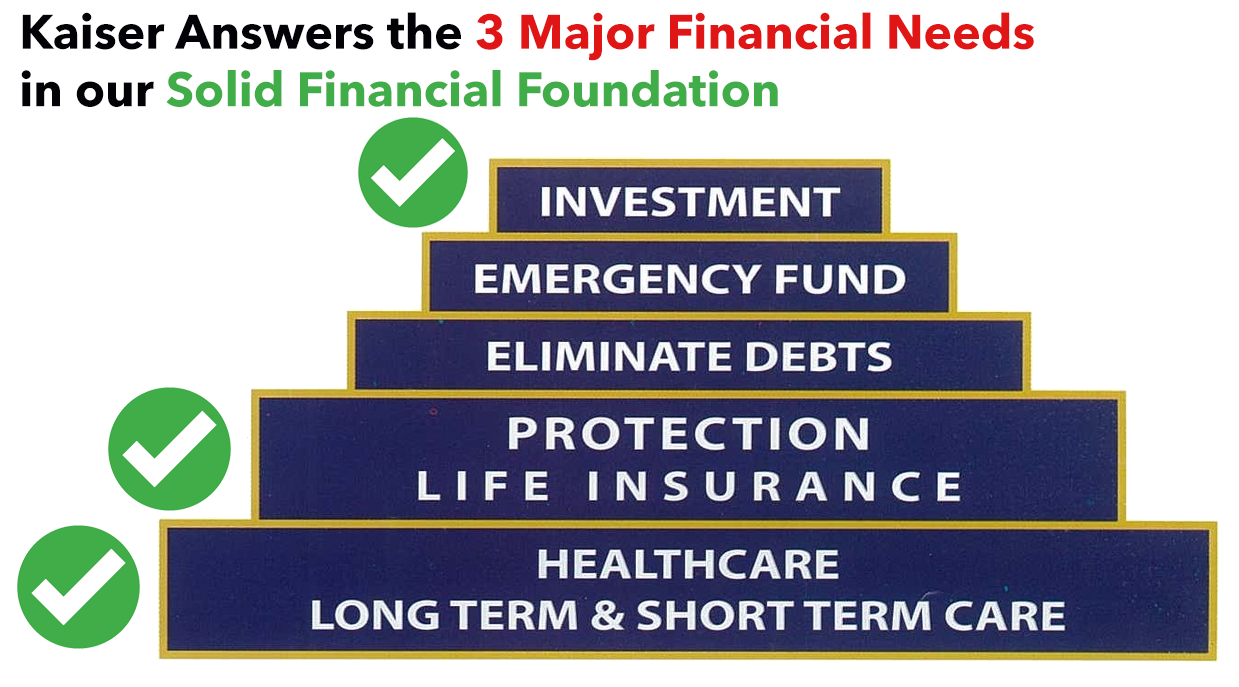
Bakit nga ba maganda magkaroon ng Kaiser 3-in-1 Investment Product ang bawat miyembro ng Pamilya lalo na yung mga bread winner?
1.
✔Kapag hindi ka na employed at binawi na nung dati mong employer yung shorterm HMO mo, hindi ka magwoworry kung maospital ka.
✔Kapag hindi mo nagamit ang annual health care coverage mo hindi sya naeexpire unlike short-term health care (HMO) na no refund ang premiums magamit muman or hindi. Sa Kaiser marereceive mo ang guaranteed Long-term care bonus (cash) sa maturity.
2.
✔May kasama na syang life insurance for income replacement or protection para sa family just in case may nangyari sa policy holder.
✔Waived na ang payment kung may nangyari sa policy holder, means wala ng babayaran ang family kahit 1 year palang nakakainvest ang policy holder, ma transfer pa ang health care coverage sa beneficiary.
3.
✔Nakainvest sa mutual fund ang health fund kaya nag-eearn sya ng 3% - 10% rate of returns depende sa performance ng stock market.
✔Good as cash sya pagdating ng maturity, So pwede kang mag-withdraw gamit ang iyong visa card. Hanggat may fund ang account mo, patuloy lang ang pag-earn ng 10% rate of returns (compounded) annually.
4.
✔Covered ka kahit beyond 60 years old ka na, as long as you live at may fund ang iyong acçount!
✔Maari kang magkaroon nito sa halagang P88.23 a day mas mahal pa ang 1pc chic N' joy na may drinks & fries bes?
MGA BENEPISYO
HEALTHCARE
Magagamit mo after one year ka na nakabayad or yearly ang binayad. At nag i increase ang healthcare benefits depende sa plan mo once fully paid
TERM LIFE INSURANCE
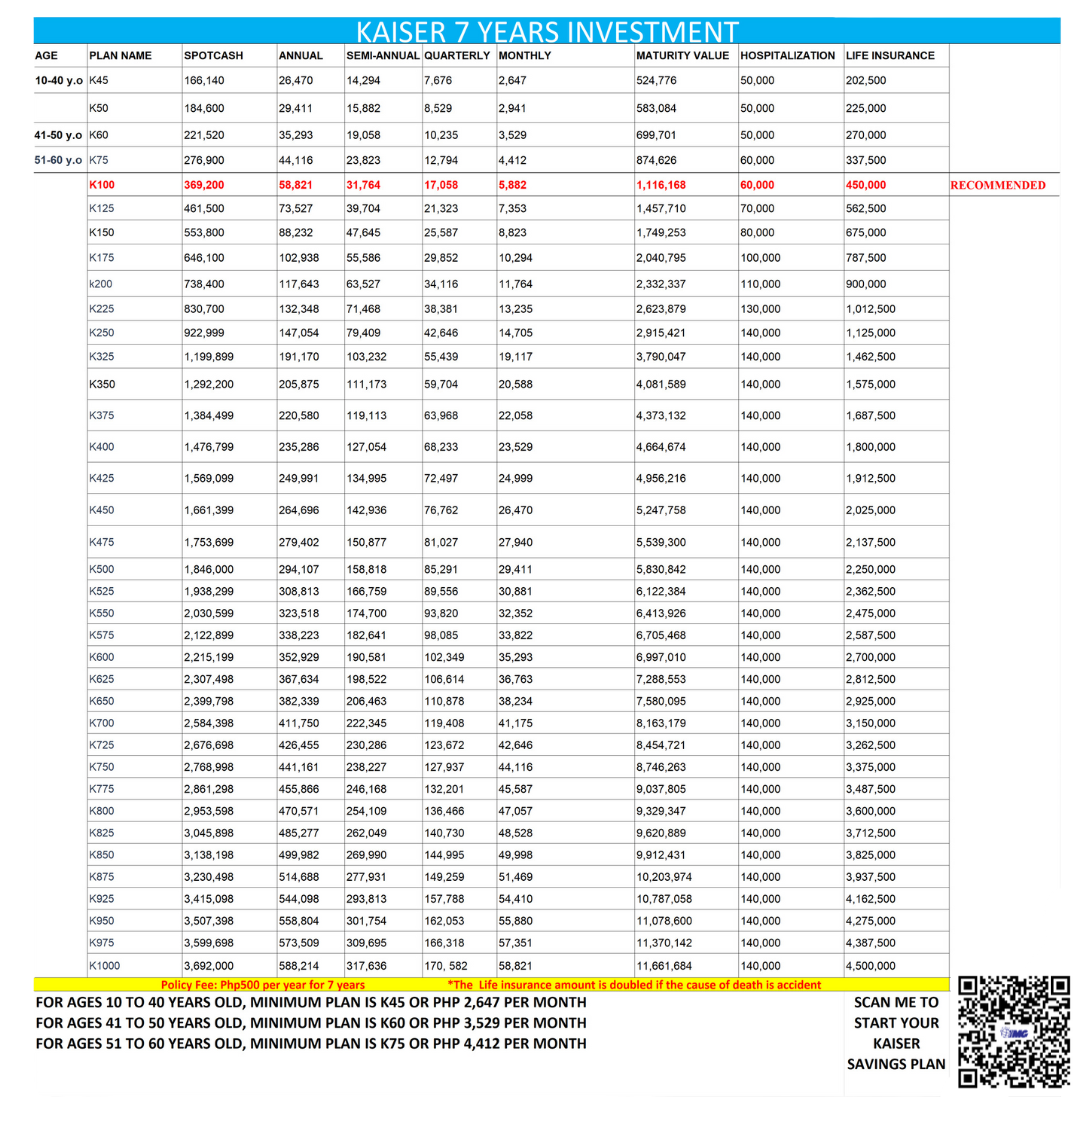
Minimum 205,500 ang benepisyo ng pamilya the moment na nakapagbayad ka you are covered kahit nasa abroad ka pa. Subject to contestability period..
ACCIDENTAL DEATH BENEFITS
Doble ang matatanggap na benefits ng beneficiary once accident ang kinamatay ni Planholder the moment na ang policy nya ay na approved na.
TRANSFERABLE
Once namatay si planholder lahat ng benefits ay ma transfer kay primary beneficiary during and after paying period.
RETIREMENT SAVINGS
Kumpletong package na eto kapag ikaw ay nagretiro. May savings ka na, Health Insurance at Investment pang kasama.
ONLINE ACCESS
Hassle free na. Dahil lahat ay ma access mo sa sarili mong portal or account. Maging sa pagbabayad.
LONG TERM CARE BONUS
85%
nang binayad mo ay babalik sayo pagdating ng maturity once hindi mo nagamit during paying period 411,750 (PLAN K100) = 350,000 (85%)
BENEPISYO HABANG NAGBABAYAD
1.
Free Dental Health Benefits once a year.
2.
Minimum 50,000 pesos a year magagamit sa ospital depende sa plan na kinuha.
3.
Free Annual Physical Examination sa Kaiser medical Center or accredited clinic at Ospital sa inyong lugar.
4.
202,500 pesos minimum TERM LIFE INSURANCE
5.
202,500 pesos minimum ACCIDENTAL DEATH BENEFITS
BENEPISYO MATAPOS MABAYARAN
1.
Pre existing illness ay covered na kahit malala pa.
2.
Term Life and Accidental benefits ay still covered hanggang maturity.
3.
May 10% yearly healthcare hospital benefits limit na or interest.
4.
Any related to Maternity ay covered.
5.
May additional 6% yearly healthcare benefit din subject for provisions depende sa takbo ng market.
6.
85% may long term care bonus ka. kung di mo ginamit ang kaiser habang nagbabayad ka pa.
MAY KAISER LONG-TERM HEALTHCARE KA NA BA?
HOW TO START YOUR KAISER SAVINGS PLAN?
ONLINE REGISTRATION
Pwede ka mag-enroll ng Kaiser Saving Plan mo through Online Kaiser Application.
Click the link below for instructions..